August 2026 Market Update
By Lock Bingham, CRPS®, CPWA® | September 2, 2026

August was another example of the idea that strong markets do not require a perfect setup. While there continues to be uncertainty around oil prices, the Fed, new tariffs affecting global trade, and interest rates that are at their highest in decades, many positive factors drove broad market indices higher.
For investors, the key takeaway is that short-term concerns are a normal part of markets. Rather than try to navigate each challenge, history shows that portfolios built around long-term goals are the best way to increase the probability of financial success.
Key Market and Economic Drivers in August
- The S&P 500, Nasdaq, and Dow Jones Industrial Average rose 2.6%, 3.9%, and 1.3%, respectively, in August. Year-to-date, they have gained 12.3%, 13.5%, and 10.7%, respectively.
- Volatility, as measured by the CBOE VIX index, dropped below the long-term average, ending the month at 16 after climbing as high as 21 the previous month.
- International developed markets returned 1.8% based on the MSCI EAFE Index in U.S. dollar terms, while emerging markets returned 3.2% based on the MSCI EM Index.
- The 30-year Treasury yield reached its highest level since 2007, closing the month at 5.24%. The 10-year Treasury yield ended the month at 4.75%. The Bloomberg U.S. Aggregate Bond Index returned 0.4% for the month.
- Oil prices hovered in a range in August after climbing the previous month. Brent crude closed the month at $90.68 per barrel and WTI near $86.27 per barrel.
- The U.S. Dollar Index fell to 99.43 at the end of August. Gold ended the month at $4,437.38 per ounce while silver rose to $66.58 per ounce.
- The revision to second quarter GDP remained unchanged at an annual rate of 1.5%.
- The July jobs report missed expectations with a decline of -23,000 in payrolls compared to a forecasted gain of 80,000. Unemployment fell slightly to 4.1%.
Long-term yields are near multi-decade highs
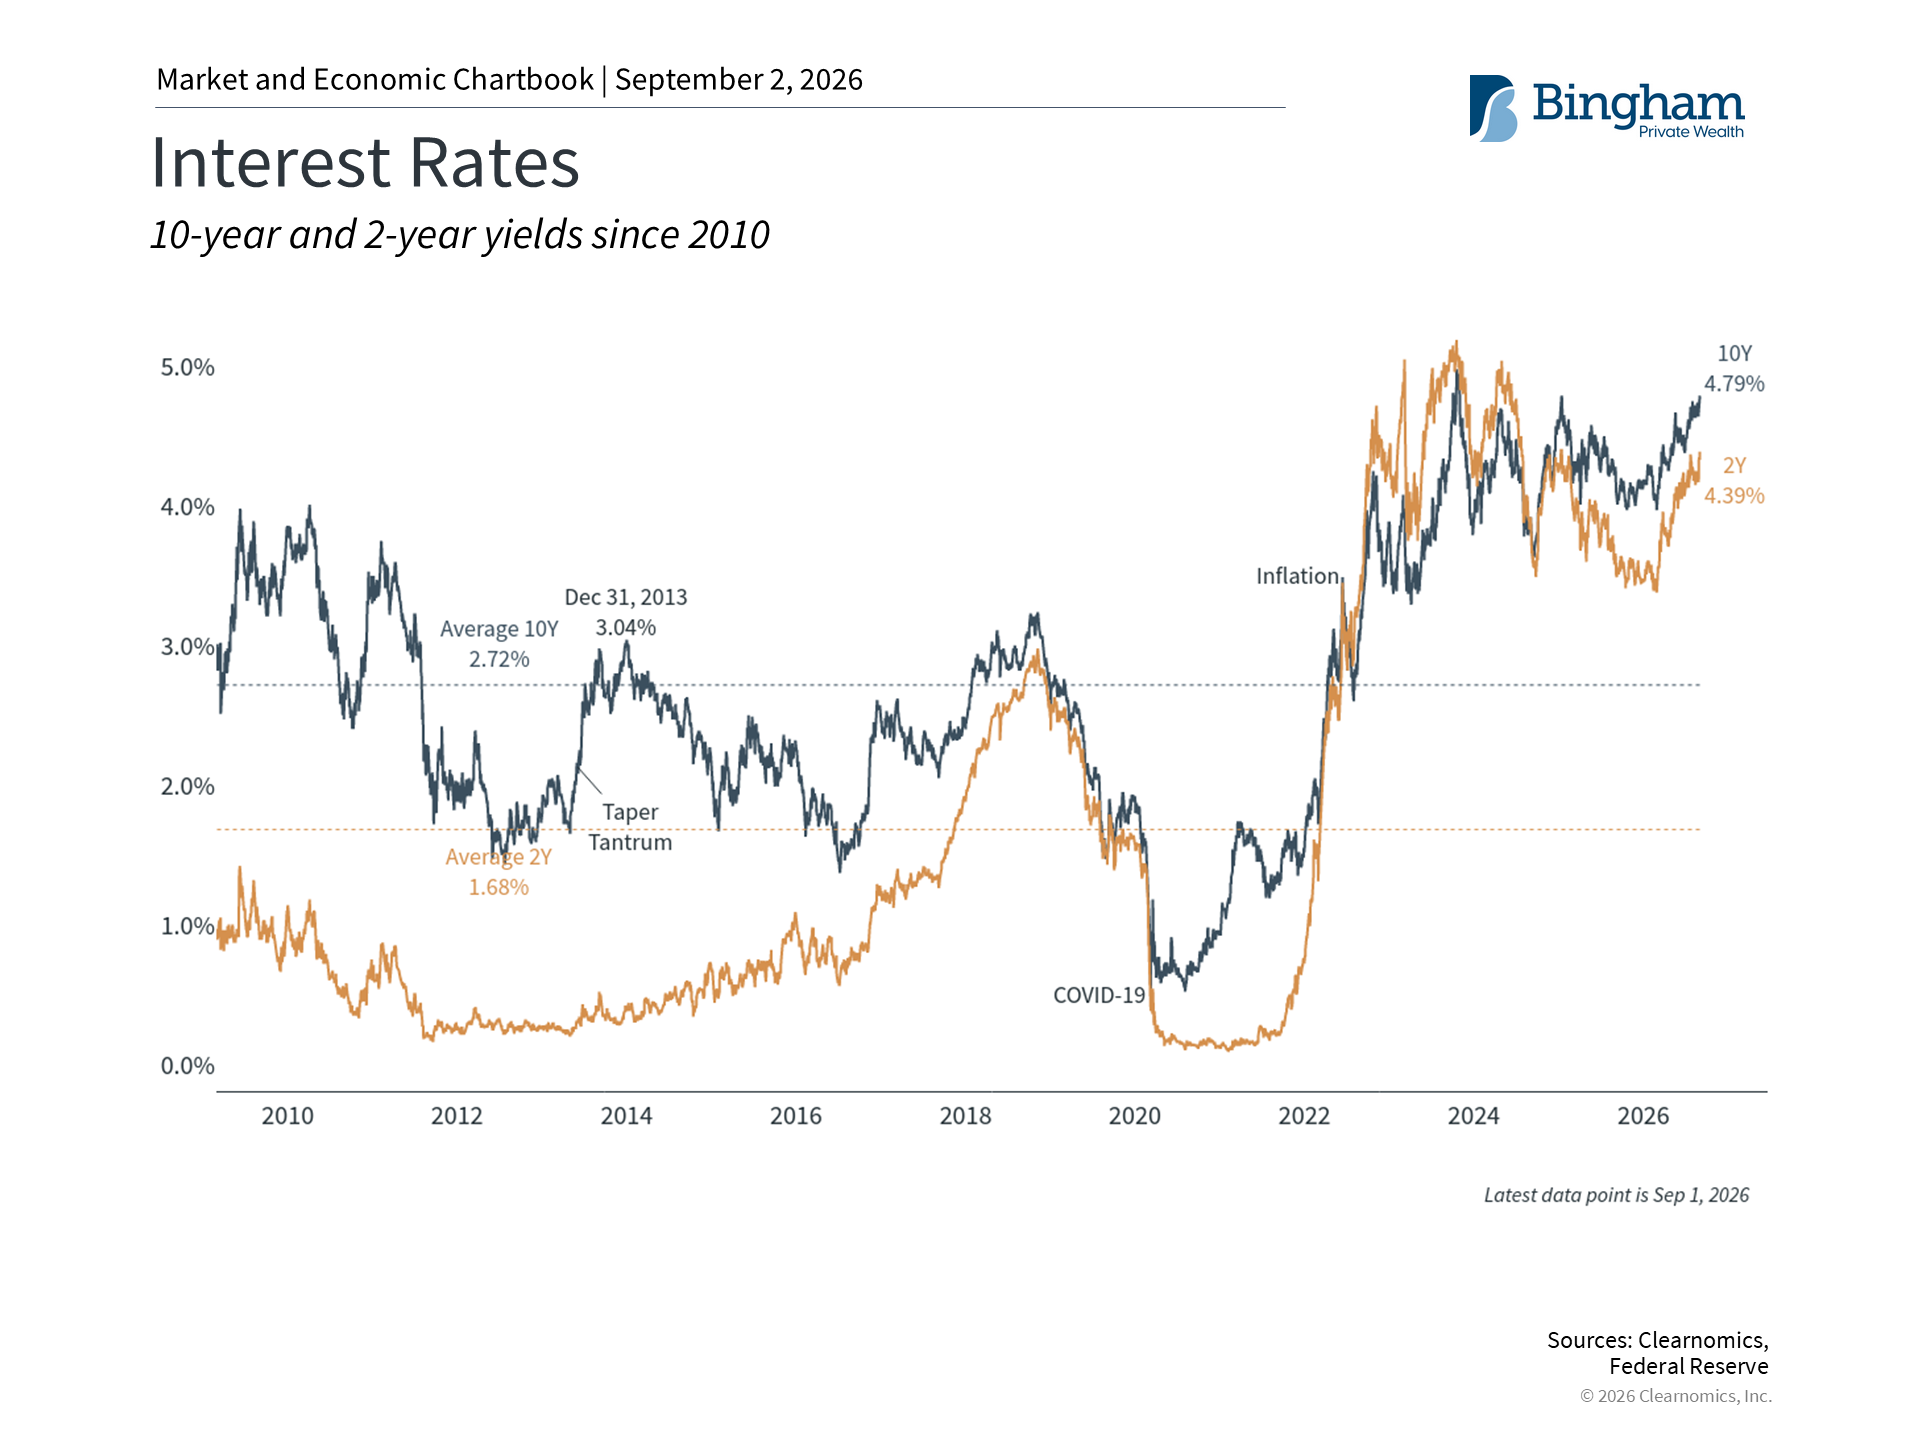 |
One of the defining features of today’s investment environment is that interest rates have remained higher than many expected. The 30-year Treasury yield briefly surpassed 5.3% in August, a level not seen in almost 20 years. Similarly, the 10-year Treasury yield, around 4.8%, is close to its recent peak.1 This is important because, while interest rates can seem technical, they both affect and are a reflection of the economy.
Often, higher rates are viewed as being negative for markets, but the key is that interest rates can rise for different reasons. While inflation drove rates higher over the past several years, more recent rate increases have occurred because “real yields” have improved. This is another way to say that inflation-adjusted yields are higher, reflecting the fact that the economy continues to be healthy, especially due to strong corporate earnings. In the long run, this is a positive signal for the overall health of the market, which is why interest rates and the stock market are near their peaks at the same time. We’ve seen in the past when interest rates can rise while stock prices rise at the same time generally due to rising corporate earnings expectations.
Looking forward, higher rates can also be positive for long-term investors because they create income opportunities across bond holdings. Of course, rising interest rates also weigh on the prices of existing bonds. This has caused major bond indices, such as the Bloomberg U.S. Aggregate Bond Index, to remain flat this year. So, it’s important to interpret rising rates in the context of a well-balanced portfolio and relative to financial goals.
That said, inflation still remains higher than consumers and policymakers would like. The headline Personal Consumption Expenditures Price Index, for example, showed that inflation stood at 3.7% year-over-year in July, while core PCE rose 3.3%, both well above the Fed’s 2% target.2 At the Fed’s annual Jackson Hole symposium in late August, Fed Chair Kevin Warsh signaled that a rate hike could arrive sooner. For this reason, markets are now pricing in at least one rate hike this year, and possibly two by early next year.3
Corporate earnings are delivering broad-based growth
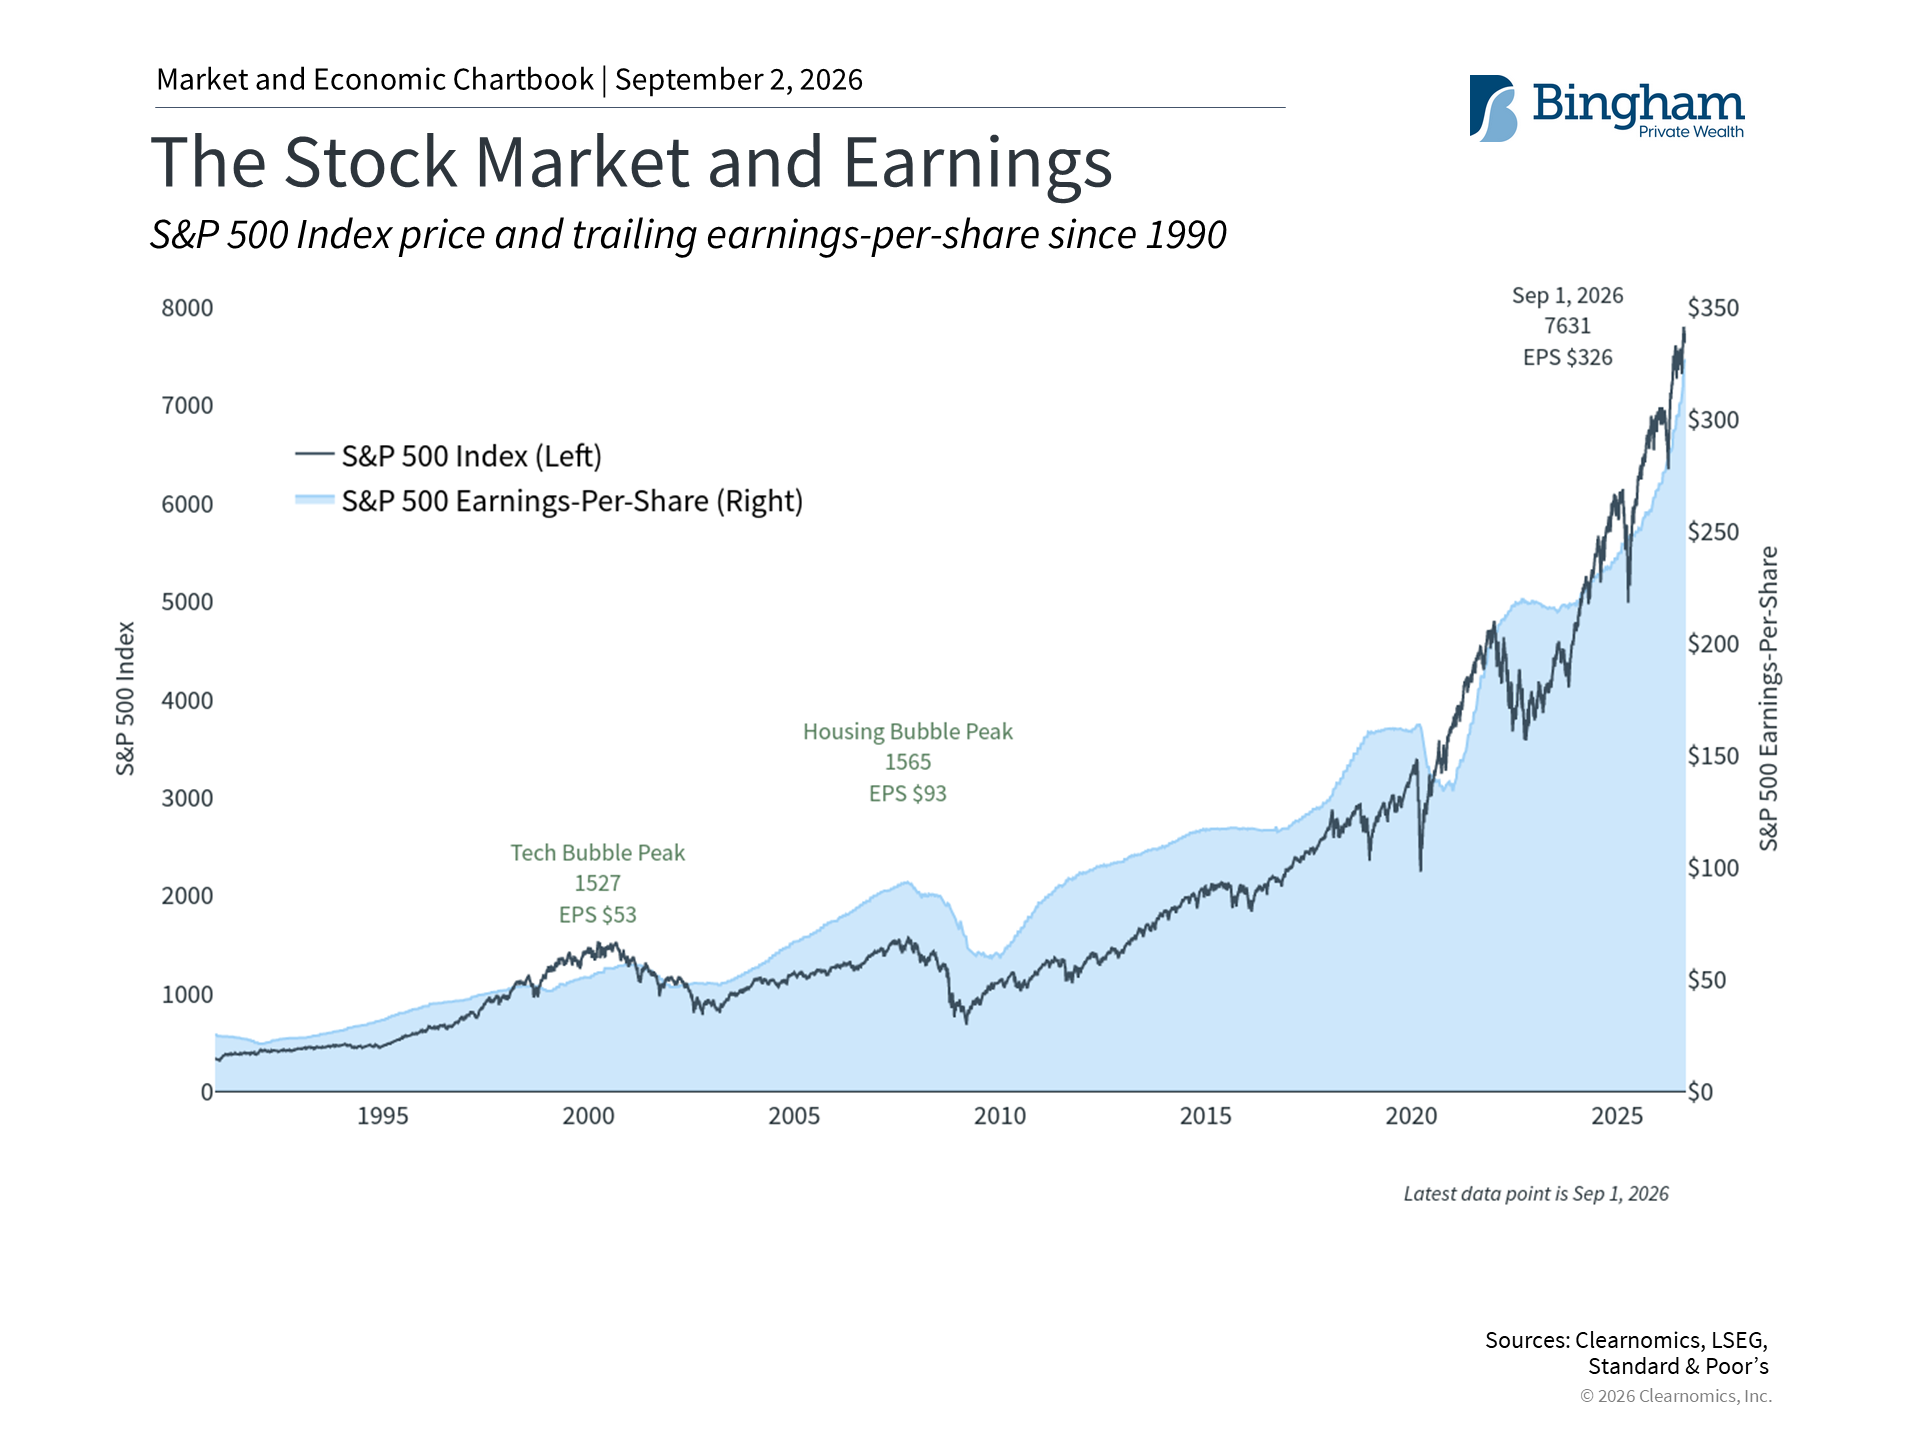 |
The S&P 500 reached new all-time highs in August, driven largely by strong corporate earnings. Results for the second quarter have come in well above expectations across a wide range of sectors, and consensus estimates now anticipate S&P 500 earnings to reach $349 per share at the end of the year. These same forecasts expect earnings-per-share growth of 15% each of the next two years as well, above the historical average of 7%.4
While these forecasts can change, they reflect growth driven by AI infrastructure buildouts, higher oil prices, and healthy growth across sectors. Specifically, ten of the eleven S&P 500 sectors reported year-over-year earnings growth, with nine reporting double-digit percentage gains. This breadth of earnings growth suggests that the overall economy, not just a narrow group of large companies, is contributing to corporate profitability.5
Strong corporate earnings are one reason that broad stock market valuations have remained steady over the past year. The S&P 500 price-to-earnings ratio has hovered around 20x, which is well above the historical average of 16x, but an improvement from recent peaks. While valuations do not predict what the market will do in the short run, they are important guides to allocating assets in the long run. In an environment of higher valuations, it’s important to stay balanced across sectors, asset classes, and geographies.
Trade tensions are still a source of uncertainty
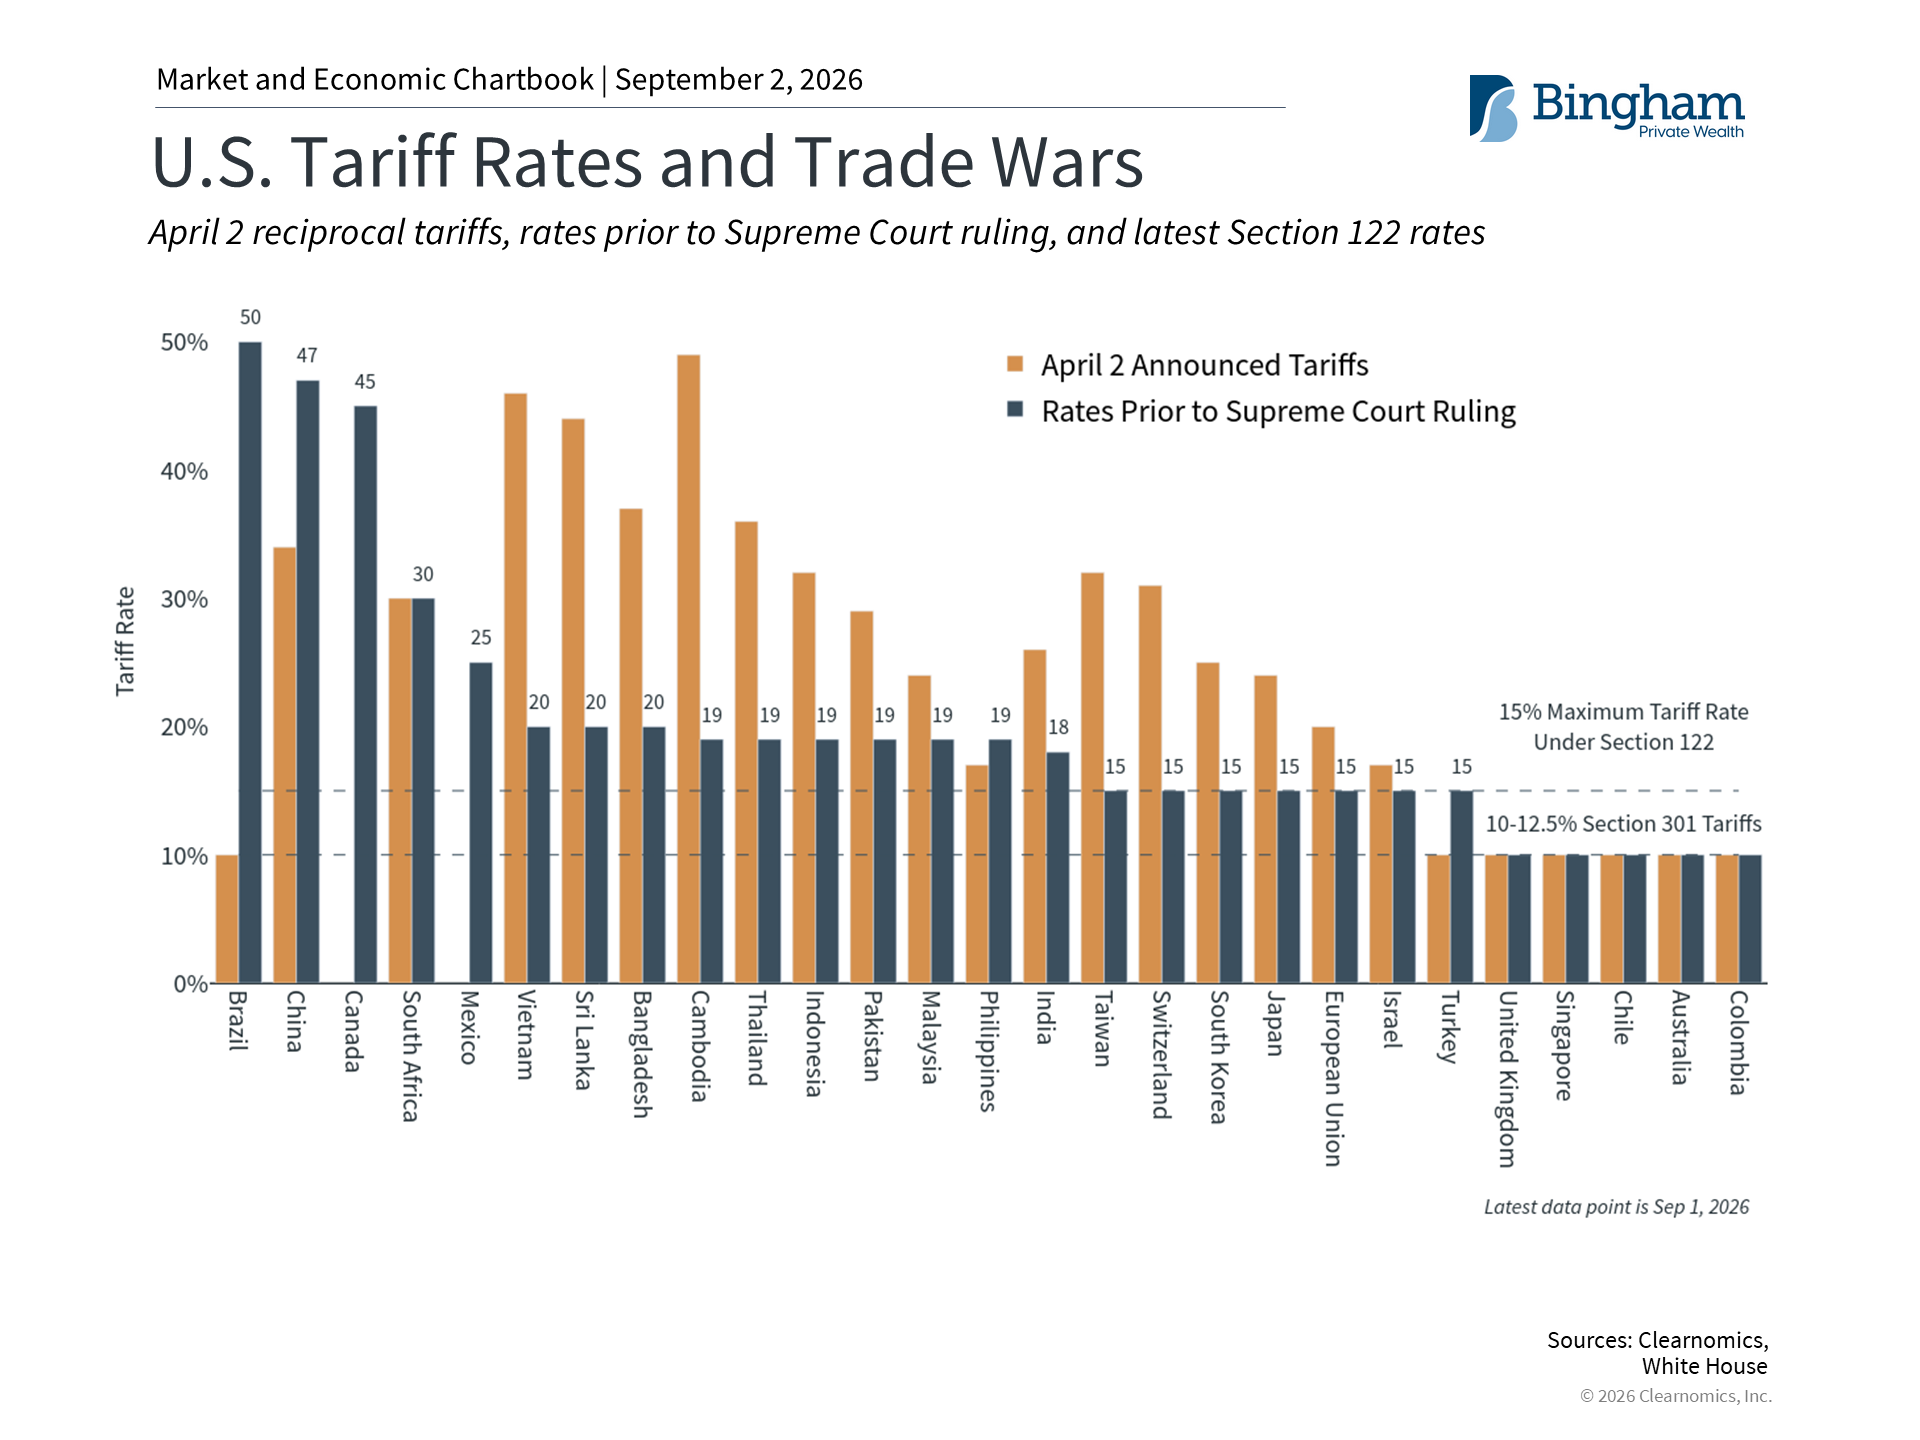 |
Trade policy returned to the headlines in August as tensions with key trading partners such as Canada escalated. After last year’s “Liberation Day” tariffs were ruled to be illegal by the Supreme Court in February, new tariffs were implemented under different laws such as Section 301 of the Trade Act of 1974. However, those tariffs have now expired, so new ones have been implemented in their place under different trade laws, each with their own set of rules. At the same time, the government is now refunding the original “reciprocal tariffs” to businesses, with $129 billion already accepted for processing by U.S. Customs and Border Protection.6
As has been the case since early last year, the worst-case outcomes that many investors and economists feared have not occurred. This is largely because companies have adapted their supply chains, adjusted pricing strategies, and managed costs in reaction to these tariffs, muting the effect on inflation from higher intermediate prices. Still, tariffs will likely remain a source of uncertainty for global markets in the coming years.
The bottom line? August demonstrated the importance of staying balanced and not overreacting to headlines. Despite periods of volatility, strong corporate earnings and attractive bond yields continue to support long-term portfolios.
References
1. https://home.treasury.gov/policy-issues/financing-the-government/interest-rate-statistics
2. https://www.bea.gov/news/2026/personal-income-and-outlays-july-2026
3. https://www.cmegroup.com/markets/interest-rates/cme-fedwatch-tool.html
4. Clearnomics research and LSEG data as of August 31, 2026
5. https://insight.factset.com/sp-500-earnings-season-update-august-7-2026
6. https://www.cbp.gov/trade/programs-administration/trade-remedies/ieepa-duty-refunds
Index Descriptions
S&P 500
The Standard & Poor’s 500 Index is a capitalization-weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries.
Dow Jones
The Dow Jones Industrial Average is comprised of 30 stocks that are major factors in their industries and widely held by individuals and institutional investors.
NASDAQ
The NASDAQ Composite Index measures all NASDAQ domestic and non-U.S. based common stocks listed on The NASDAQ Stock Market. The market value, the last sale price multiplied by total shares outstanding, is calculated throughout the trading day, and is related to the total value of the Index.
MSCI Emerging Markets Index
The MSCI EM (Emerging Markets) Index is a free float-adjusted market capitalization weighted index that is designed to measure the equity market performance of the emerging market countries of the Americas, Europe, the Middle East, Africa and Asia. The MSCI EM Index consists of the following emerging market country indices: Brazil, Chile, Colombia, Mexico, Peru, Czech Republic, Egypt, Greece, Hungary, Poland, Qatar, Russia, South Africa, Turkey, United Arab Emirates, China, India, Indonesia, Korea, Malaysia, Philippines, Taiwan, and Thailand.
MSCI EAFE Index
The MSCI EAFE Index is a free float-adjusted market capitalization index that is designed to measure the equity market performance of developed markets, excluding the US & Canada. The MSCI EAFE Index consists of the following developed country indices: Australia, Austria, Belgium, Denmark, Finland, France, Germany, Hong Kong, Ireland, Israel, Italy, Japan, the Netherlands, New Zealand, Norway, Portugal, Singapore, Spain, Sweden, Switzerland and the UK.
DXY
The DXY is a U.S. dollar index based on a basket of currencies, including the Euro, Yen, Pound, Canadian Dollar, Swedish Krona and Swiss Franc.
Certain market commentary, charts, and economic content contained herein are provided by Clearnomics, Inc. and are used with permission. Powered by Clearnomics.
The information is for informational and educational purposes only and should not be construed as investment advice or a recommendation to buy or sell any security. Past performance is not indicative of future results. All investing involves risk, including the possible loss of principal.
Bingham Private Wealth, LLC (“BPW”) is a registered investment advisor. Advisory services are only offered to clients or prospective clients where BPW and its representatives are properly licensed or exempt from licensure.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such.
The views expressed in this commentary are subject to change based on market and other conditions. These documents may contain certain statements that may be deemed forward looking statements. Please note that any such statements are not guarantees of any future performance and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.